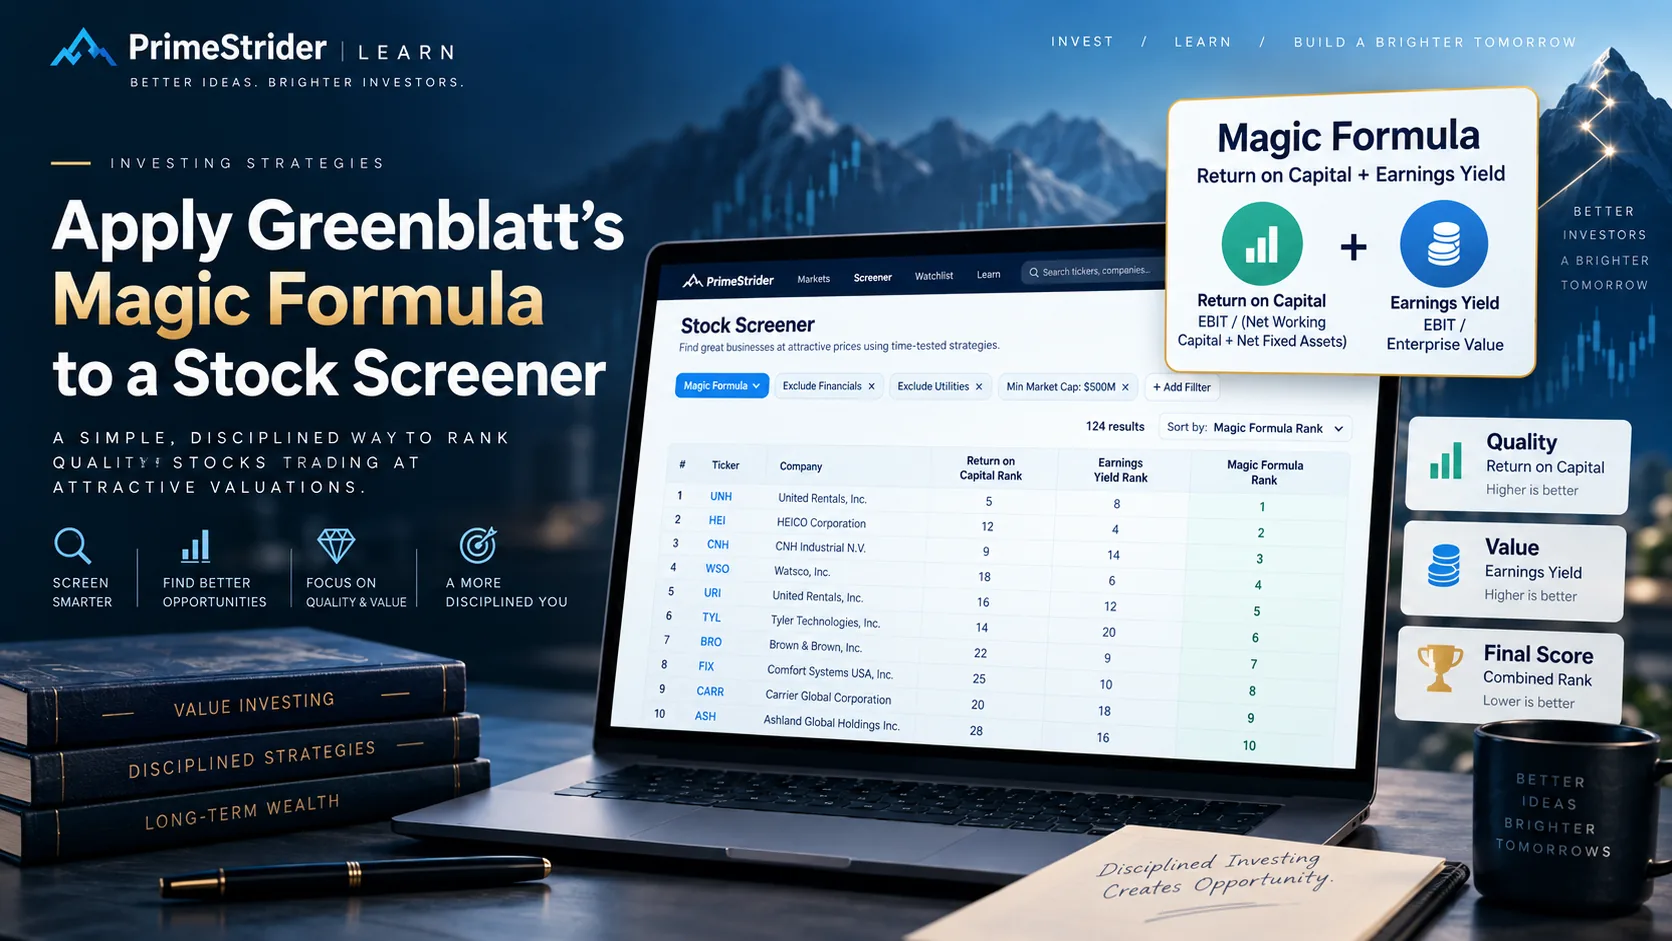
Finding cheap stocks is easy. Finding high-quality companies is easy. Finding businesses that are both good and attractively priced is much harder.
That is the idea behind Joel Greenblatt's Magic Formula. Popularized in The Little Book That Beats the Market, the strategy ranks companies on two dimensions at the same time: the quality of the business and the price investors are paying for it.
Return on Capital
Higher is better
Earnings Yield
Higher is better
Best balance first
Research the leaders
This guide explains the logic, shows how to reproduce it in PrimeStrider, and proposes practical variants for investors who want to add growth, momentum, or simpler metrics. Beginner? Follow the numbered build. Already comfortable with screeners? Use the methodology notes, exclusions, and variants to stress-test the model.
The key distinction: filters decide which companies are eligible; ranking decides which eligible companies offer the strongest quality/value combination.
The Magic Formula in one sentence
The strategy looks for companies with high operating profitability that trade at low valuations.
It does this with two factors:
- Business quality: Return on Capital.
- Valuation: Earnings Yield based on Enterprise Value.
Every eligible company is ranked on each factor. The two ranks are then combined, and the companies with the best total ranking rise to the top.
Step 1: measure business quality
The original Magic Formula uses a version of Return on Capital. Its purpose is to answer a simple question:
How much operating profit does the company generate from the capital required to run the business?
Return on Capital
EBIT ÷ Invested Operating Capital
Higher is better
Earnings Yield
EBIT ÷ Enterprise Value
Higher is better
The higher the return, the more efficiently the company converts its operating assets into profit. In a universe of 1,000 stocks, the company with the highest Return on Capital receives Quality Rank 1, the second receives Rank 2, and so on.
This is a relative measure. The method does not require an arbitrary rule such as Return on Capital above 20%. It asks which businesses are best compared with the alternatives available today.
Step 2: measure valuation with Earnings Yield
The valuation factor asks a different question:
How much operating profit are we receiving relative to the price of the entire business?
The classic formula is:
Earnings Yield = EBIT / Enterprise Value
Enterprise Value includes the market value of equity, debt, and cash. That makes it more suitable than a simple P/E ratio when comparing companies with different capital structures.
The company with the highest Earnings Yield receives Valuation Rank 1. A high Earnings Yield generally means the business is cheaper relative to its operating profit. If your screener offers EV/EBIT instead, use the inverse direction: lower is better.
Step 3: combine the rankings
For each company:
Magic Formula Rank = Quality Rank + Valuation Rank
Beta is an exceptional business, but investors are already paying a very high price for it. Gamma looks extremely cheap, but its underlying economics are weaker. Alpha is not number one on either factor, yet it offers the strongest combination of quality and value.
That is the central insight of multi-factor ranking: a balanced candidate can be more attractive than a company that looks extraordinary on only one dimension.
Why ranking is different from filtering
A traditional screener might require:
- Return on Capital above 20%.
- Earnings Yield above 6%.
Those rules are useful, but thresholds create hard boundaries. A company with a 19.9% Return on Capital disappears, while one at 20.1% remains, even if the first company is much cheaper.
Ranking avoids this cliff effect. Instead of asking, Does this company pass my minimum requirement?, it asks, How attractive is this company compared with everything else in the same universe?
The best screen often uses both tools: filters define what is eligible, while scoring determines what is most attractive.
How to build the Magic Formula in PrimeStrider
In PrimeStrider, reproduce the logic with a broad universe, a few eligibility filters, and a two-factor scoring profile.
1. Define the investable universe
Start broad enough for relative ranking to be meaningful, but remove securities you would not realistically own. A practical starting point is:
- Market capitalization above $500 million to reduce micro-cap and liquidity risk.
- Positive EBIT so Earnings Yield is economically meaningful.
- Positive Enterprise Value to avoid distorted ratios.
- Sufficient financial history and data coverage.
You may also screen financial companies and utilities separately. Banks, insurers, and heavily regulated utilities use capital differently, so EBIT/Enterprise Value and conventional Return on Capital are not always directly comparable with industrial or technology companies.
2. Add the quality factor
Add Return on Capital or the closest available Return on Invested Capital metric to the scoring profile. Configure the direction so that higher values receive better scores.
3. Add the valuation factor
Add Earnings Yield and configure higher is better. If you use EV/EBIT instead, configure lower is better.
4. Set equal weights
Equal weighting prevents an extremely cheap but weak business from dominating the screen, and it prevents an excellent but excessively valued company from winning on quality alone.
5. Rank, then investigate
Sort the results by the combined PrimeStrider score. The top 20 to 30 names are a research list, not an automatic buy list. Open each company and review earnings quality, leverage, cyclicality, recent filings, and any event that may explain an unusually cheap valuation.
Before saving the screen, verify:
✓ Quality ranks higher values first
✓ Earnings Yield ranks higher values first or EV/EBIT ranks lower values first
✓ Weights total 100%
✓ EBIT and Enterprise Value are positive
✓ Financials and special sectors are handled deliberately
Classic PrimeStrider setup
Useful Magic Formula variants
Run each variant as a separate saved profile. Keep the universe, rebalance date, factor directions, and missing-data rules constant. Otherwise, differences in the results may come from the test design rather than the factors themselves.
The original model is a strong starting point, but PrimeStrider makes it easy to test variations. Give each version a separate scoring profile so you can compare the rankings without changing your original screen.
Variant 1: the accessible Quality + Value model
This version is intuitive and uses widely available metrics. However, it is inspired by the Magic Formula rather than a faithful reproduction. Debt can inflate ROE, while P/E ignores the balance sheet and uses net income instead of operating profit.
Variant 2: add growth and momentum
This model asks four questions: Is it a good business? Is it reasonably priced? Is it growing? Is the market beginning to confirm the thesis? The extra factors can reduce exposure to stagnant value traps, but they also move the strategy further away from Greenblatt's original design.
Variant 3: quality first
This version may suit investors who are willing to pay a fairer price for durable compounders. It will usually surface fewer deep-value names and more consistently profitable businesses.
Variant 4: value first
This more contrarian version emphasizes cheapness while retaining a minimum quality discipline. Expect more cyclical and turnaround candidates, and perform additional work on debt, normalized earnings, and the reason for the discount.
Filters to apply before scoring
Ranking does not make filters obsolete. Use filters for characteristics that should make a company ineligible, then use scoring to rank the survivors.
- Exclude negative EBIT.
- Exclude extremely small or illiquid companies.
- Require adequate reporting history.
- Remove companies with obviously unusable Enterprise Value data.
- Consider separate screens for financials, utilities, and highly cyclical commodity producers.
Do not over-filter. If the initial universe becomes too narrow, rankings lose much of their comparative value and the screen may merely confirm assumptions you placed into the rules.
Common mistakes
- Mixing incompatible directions: Earnings Yield should rank high to low; EV/EBIT should rank low to high.
- Using ROE without checking leverage: a small equity base or heavy debt can make ROE look exceptional.
- Ignoring one-off EBIT: asset sales, temporary peaks, or accounting items can make a stock appear artificially cheap.
- Comparing unlike sectors: capital intensity and accounting conventions vary widely.
- Treating the top rank as a recommendation: the score identifies candidates for research; it does not assess every risk.
- Changing the model after seeing the results: save clear profiles and compare them consistently to reduce hindsight bias.
How to compare your profiles
Create three saved PrimeStrider profiles:
- Classic: 50% Return on Capital, 50% Earnings Yield.
- Simple Quality Value: 50% ROE, 50% P/E.
- Extended Quality Value: quality, valuation, growth, and momentum.
Then compare the top-ranked companies. Which names survive all three methods? Which only appear because they are extremely cheap? Which expensive companies remain because their quality is exceptional? Which names become stronger when growth and momentum are introduced?
The overlap is often more informative than any single score. A company that ranks well under several reasonable definitions may deserve priority in your research queue.
Key takeaway
The Magic Formula turns a vague principle — buy good companies at attractive prices — into a reproducible ranking system:
Define the universe → apply eligibility filters → measure quality and value → rank the companies → combine the scores → investigate the strongest candidates.
Its greatest lesson is methodological. Relative rankings can be more informative than arbitrary cutoffs, one metric rarely tells the whole story, and multiple dimensions can balance one another. Once the framework exists in PrimeStrider, you can keep the classic formula or adapt it with growth, momentum, financial strength, and different factor weights.
Screening and scoring are research tools, not investment recommendations. Results depend on the selected universe, data definitions, methodology, and update date. Always perform further analysis before making an investment decision.