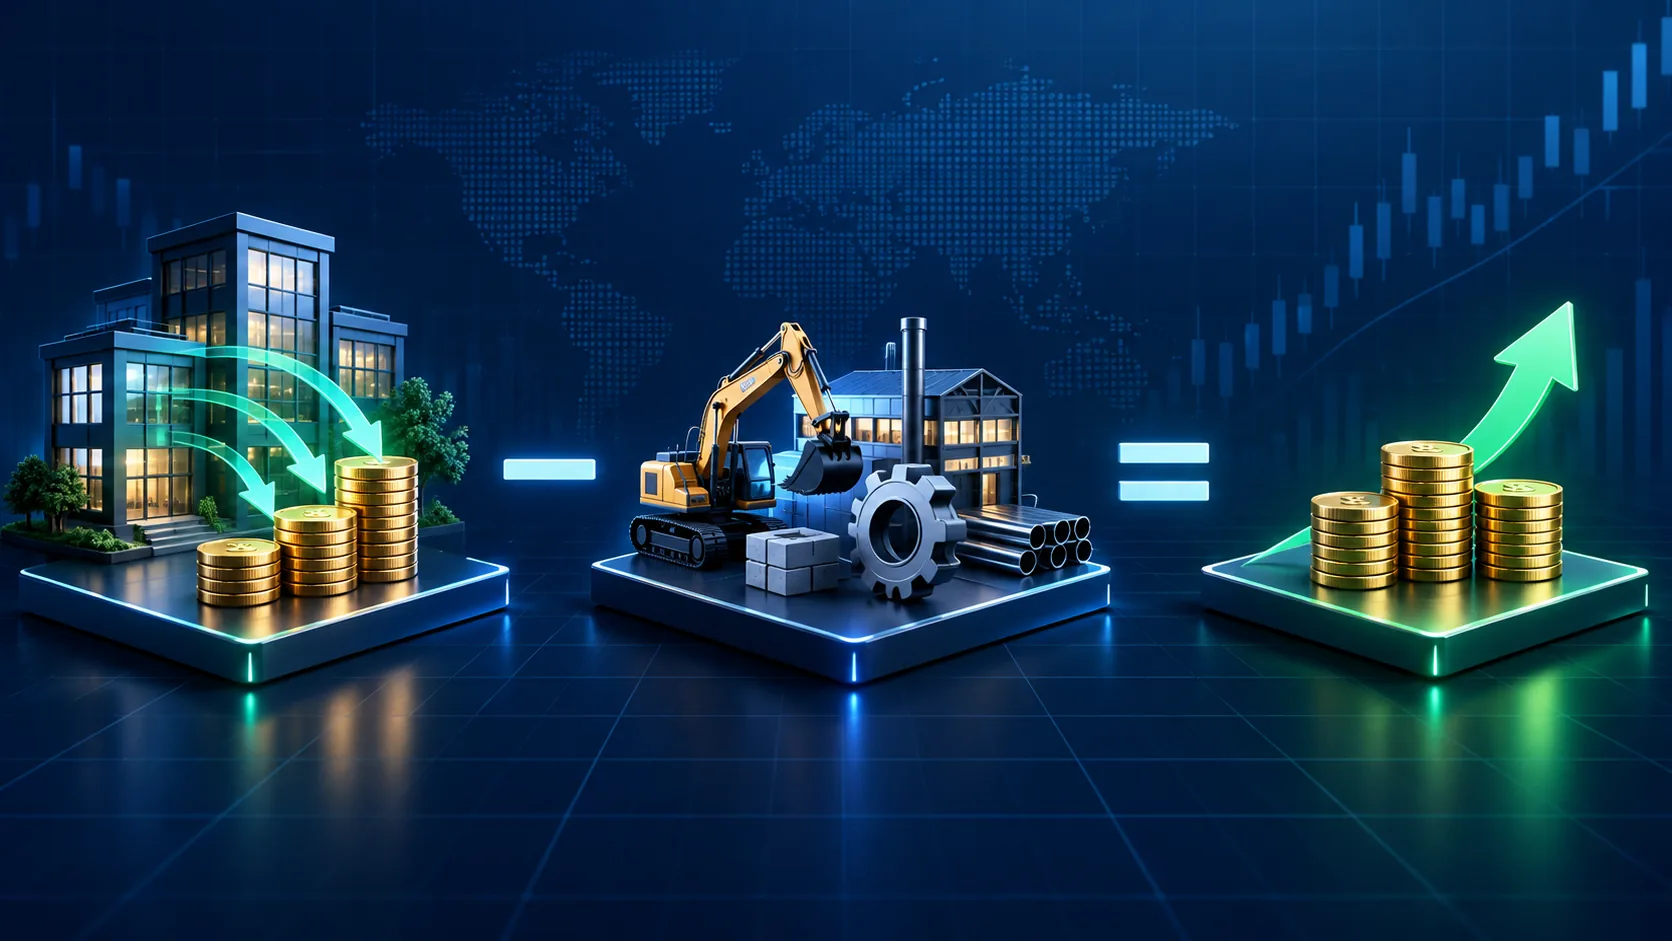
A company can report rising profits and still struggle to generate cash. Free Cash Flow (FCF) helps investors look beyond accounting earnings and understand how much cash a business actually produces after funding the investments required to operate.
What is Free Cash Flow?
Free Cash Flow measures the cash that remains after a company has paid for its day-to-day operations and invested in assets such as factories, equipment, infrastructure, stores, data centres or software.
This remaining cash can potentially be used to reduce debt, repurchase shares, pay dividends, acquire other businesses, build cash reserves or finance future growth.
Free Cash Flow formula
Operating Cash Flow, often abbreviated as OCF or CFO, is generally found in the cash flow statement. Capital expenditures, or CapEx, represent investments in long-term assets.
A simple Free Cash Flow example
Imagine a company generates $1.2 billion in operating cash flow during the year and spends $350 million on capital expenditures.
The company therefore generated $850 million of Free Cash Flow.
That does not automatically mean the stock is attractive. Investors still need to consider the company's valuation, debt, future investment requirements, competitive position and the sustainability of that cash generation.
Why does Free Cash Flow matter to investors?
Accounting profit includes non-cash items. FCF provides another perspective by focusing on cash actually generated by the business.
A company that requires huge annual investments may have less cash available to shareholders than its earnings suggest.
Strong cash generation can give a company the ability to repay debt or build liquidity without relying on external financing.
Excess cash may be reinvested, used for acquisitions, distributed through dividends or used for share buybacks.
Free Cash Flow vs net income
Net income and Free Cash Flow answer different questions.
| Metric | Main question | Includes non-cash accounting? | Includes CapEx? |
|---|---|---|---|
| Net Income | How profitable was the company according to accounting rules? | Yes | Not directly |
| EBITDA | How profitable are operations before interest, taxes and major non-cash charges? | Partially adjusted | No |
| Operating Cash Flow | How much cash did the company's operations generate? | Mostly cash-based | No |
| Free Cash Flow | How much cash remains after capital investment? | Mostly cash-based | Yes |
This distinction can become particularly important when reported earnings and cash generation move in different directions.
What is a good Free Cash Flow?
There is no universal FCF level that makes a company "good". A $10 billion company and a $500 million company cannot be compared simply by looking at the absolute amount of cash they generate.
Instead, investors usually examine several dimensions.
- Is Free Cash Flow consistently positive?
- Is FCF growing over several years?
- How stable is cash generation during weaker economic periods?
- How does Free Cash Flow compare with revenue?
- How does Free Cash Flow compare with net income?
- How much of the company's valuation is supported by its cash generation?
The direction and consistency of Free Cash Flow are often more informative than a single year's figure.
Free Cash Flow margin
Free Cash Flow can also be compared with revenue using the Free Cash Flow margin.
Suppose a business generates $850 million of Free Cash Flow from $5 billion in annual revenue:
FCF Margin = 850M ÷ 5B = 17%
In this example, roughly 17 cents of every dollar of revenue ultimately becomes Free Cash Flow.
However, FCF margins vary significantly between industries. Capital-intensive businesses usually require more investment than asset-light software or service companies, so cross-sector comparisons need context.
Can negative Free Cash Flow be acceptable?
Yes. Negative Free Cash Flow is not automatically a sign of a bad business.
A growing company may deliberately invest heavily in new factories, infrastructure, distribution networks or technology. These investments can temporarily reduce Free Cash Flow while potentially increasing future earnings capacity.
| Negative FCF situation | Possible interpretation |
|---|---|
| Heavy expansion CapEx | Potentially constructive if investments generate attractive future returns. |
| Rapid revenue growth | Cash may temporarily be absorbed by inventory and working capital. |
| One-off investment programme | FCF may recover when the investment cycle ends. |
| Persistently weak operations | More concerning if the core business repeatedly fails to generate sufficient cash. |
The key question is therefore not simply "Is Free Cash Flow negative?" but rather:
Free Cash Flow and company quality
For mature companies, consistently positive Free Cash Flow can be an important sign of financial quality.
A company that generates cash year after year may have more freedom to invest through downturns, reduce leverage or return capital to shareholders.
But Free Cash Flow should ideally be analysed alongside other quality indicators such as:
- Return on Invested Capital (ROIC)
- Return on Equity (ROE)
- Operating margins
- Debt levels
- Revenue and earnings growth
For example, strong FCF combined with a high ROIC may indicate that the company not only produces cash, but also deploys its invested capital efficiently.
Free Cash Flow and valuation
Free Cash Flow also becomes useful when combined with market valuation.
One common metric is Free Cash Flow Yield:
For example, if a company worth $10 billion generates $500 million of annual Free Cash Flow:
FCF Yield = 500M ÷ 10B = 5%
A higher FCF yield means the company generates more Free Cash Flow relative to its current market value. But, as with the P/E ratio, a high yield can reflect either an attractive valuation or greater business risk.
Common mistakes when using Free Cash Flow
1. Looking at only one year
Working capital movements, large investments and exceptional items can significantly influence annual cash flow. Multi-year trends are generally more informative.
2. Comparing unrelated industries
A semiconductor manufacturer, utility and software company have fundamentally different capital requirements. Their Free Cash Flow profiles should not be interpreted using identical expectations.
3. Assuming all CapEx is maintenance CapEx
The standard FCF formula subtracts total capital expenditures. However, some CapEx may finance expansion rather than simply maintain existing operations.
4. Ignoring stock-based compensation
Stock-based compensation is a non-cash expense that is added back when calculating operating cash flow. Heavy use of stock compensation can therefore make cash generation appear stronger while still diluting shareholders.
5. Ignoring debt
Two companies producing the same Free Cash Flow may have very different financial risk if one carries substantially more debt.
How to use Free Cash Flow in a stock screener
Rather than analysing FCF manually for thousands of companies, a stock screener can help narrow the universe.
Depending on your investment strategy, you might look for combinations such as:
- Positive Free Cash Flow
- Growing Free Cash Flow over several years
- Healthy FCF margins
- Positive FCF combined with high ROIC
- Strong cash generation with moderate debt
- Attractive Free Cash Flow Yield
The objective is not to find one perfect metric. It is to combine several complementary signals.
Free Cash Flow: key takeaways
- Free Cash Flow measures cash remaining after capital expenditures.
- Positive FCF can give a company significant financial flexibility.
- FCF should be analysed over several years rather than in isolation.
- Negative FCF can be acceptable when it reflects productive investment.
- Free Cash Flow becomes particularly useful when combined with quality, growth, debt and valuation metrics.
Frequently asked questions
What is Free Cash Flow?
Free Cash Flow is the cash generated by a company's operations after subtracting capital expenditures. It represents cash that may be available for debt reduction, acquisitions, dividends, buybacks or future investment.
How do you calculate Free Cash Flow?
A commonly used formula is Operating Cash Flow minus Capital Expenditures.
Is high Free Cash Flow always good?
Not necessarily. Investors should examine why FCF is high, whether it is sustainable, how much debt the company carries and whether insufficient investment could be temporarily boosting cash generation.
Can a good company have negative Free Cash Flow?
Yes. Companies investing aggressively in growth can temporarily generate negative FCF. The important question is whether those investments are likely to produce attractive future returns.
What is the difference between Free Cash Flow and net income?
Net income is an accounting measure of profitability. Free Cash Flow focuses more directly on cash generated after capital expenditures, so the two figures can differ significantly.
What is Free Cash Flow Yield?
Free Cash Flow Yield compares a company's Free Cash Flow with its market capitalisation. It helps investors evaluate how much cash the business generates relative to its stock market valuation.
This article is for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Financial metrics should be considered together with a company's business model, financial statements, valuation and individual investor objectives.