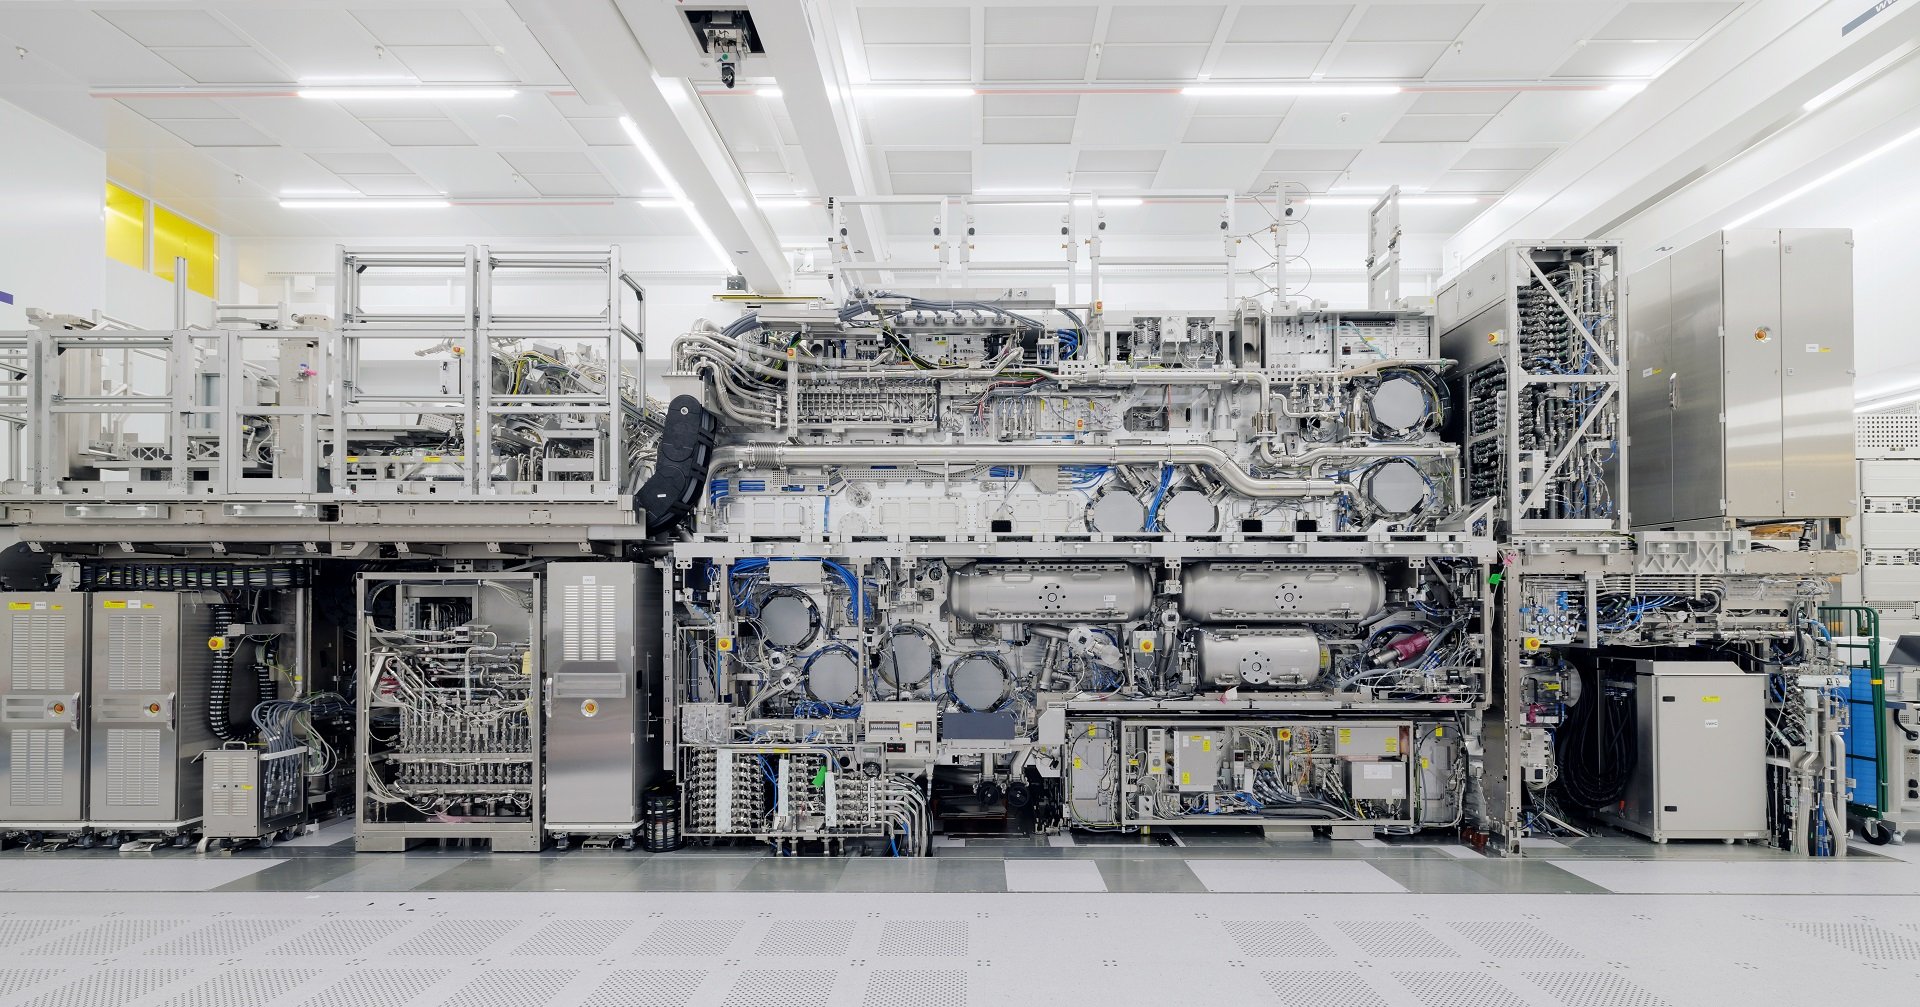
ASML reported record third-quarter 2026 net sales of €11.7 billion, a 57.5% gross margin and €5.0 billion of net income. The €1.88 interim dividend is one part of a much stronger capital-allocation and demand picture: customers are extending equipment plans into 2029 and 2030, while ASML says currently planned supply for 2027 and 2028 may not fully meet demand.
Q3 results in context
Net sales rose from €9.33 billion in Q2 to €11.66 billion in Q3. Installed Base Management sales reached €3.29 billion, supported by demand for productivity upgrades. ASML sold 113 new lithography systems and eight used systems, versus 86 and five respectively in the prior quarter.
Gross margin increased to 57.5% from 54.0%, lifting basic earnings per share to €12.95 from €7.59. Cash, cash equivalents and short-term investments ended the quarter at €12.74 billion, up from €7.58 billion at the end of Q2. The sequential comparisons are useful, but investors should remember that revenue recognition for high-value systems can make individual quarters uneven.
Guidance points to a strong finish
Management expects Q4 net sales of €14.2 billion to €15.2 billion with a gross margin around 57%. Full-year guidance is €44 billion to €45 billion of net sales and a gross margin around 56%. The central investor question is therefore not the dividend yield; it is whether ASML and its supplier network can convert exceptional AI-related demand into capacity without weakening margins or delivery reliability.
Management said customer forecasts have risen primarily because of the expected scale and duration of AI investment. ASML is examining ways to expand 2028 capacity beyond a previously communicated 30% increase. That visibility supports the bullish case, but interest in orders for 2029 or 2030 is not the same as firm, non-cancellable revenue.
Dividend and buyback
The €1.88-per-share interim dividend is payable on 4 November 2026. The shares trade ex-dividend on 26 October on Euronext Amsterdam and 27 October on Nasdaq, with a 27 October record date. ASML also repurchased about €4.1 billion of shares during Q3 under its 2026–2028 program.
Those distributions demonstrate balance-sheet capacity, but they should be assessed alongside large R&D and production investments. ASML expects roughly €1.2 billion of R&D expense in Q4 alone. Capital returns remain conditional on future liquidity, working-capital needs, capacity spending and acquisition opportunities.
Bull case, bear case and what to monitor
Bull case: AI infrastructure spending is broadening equipment demand, service revenue is supporting margins, and supply scarcity strengthens ASML's strategic position. Bear case: the valuation may already discount years of growth, customer capex could be delayed, export controls can restrict shipments, and an aggressive capacity build could raise execution risk.
Investors should monitor Q4 order intake, High-NA EUV acceptance, service and upgrade growth, customer capital-expenditure plans, export-license changes, supplier capacity and whether the 57% margin can be sustained as output ramps.
Sources: ASML Q3 2026 results; ASML capital return and dividend timetable.