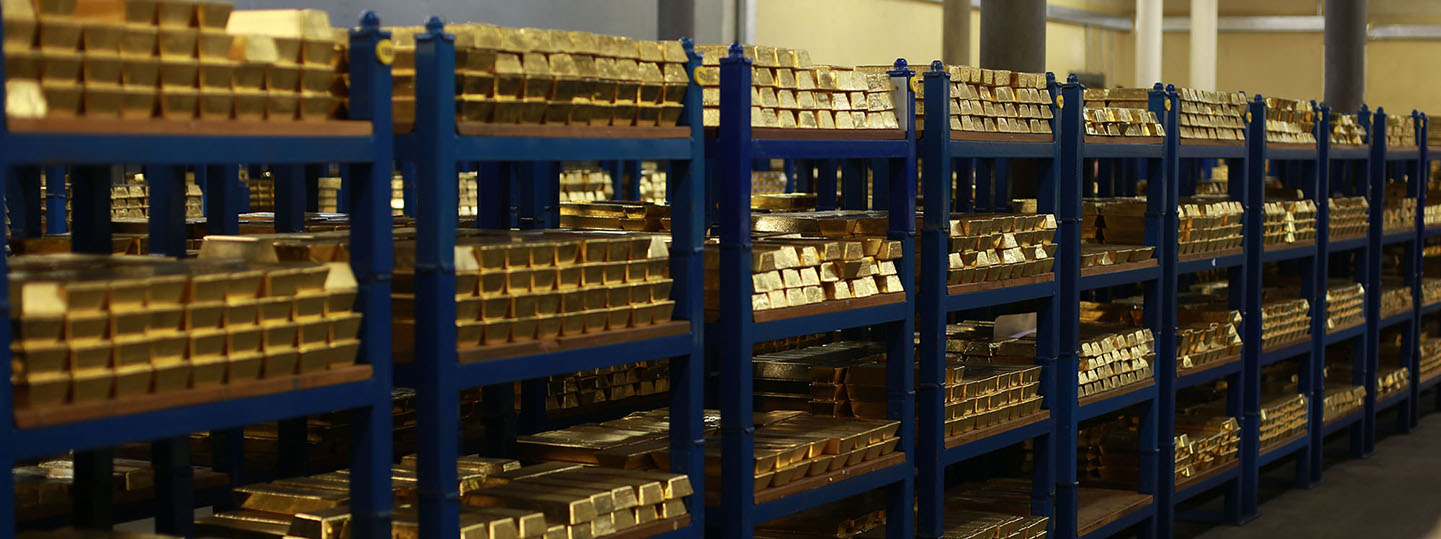
What happened: Venezuela’s government and opposition are reportedly close to an agreement to transfer about 31 metric tonnes of central-bank gold, valued at roughly $4 billion, from the Bank of England to the Federal Reserve Bank of New York. The Financial Times first reported the talks; Reuters said it could not independently verify the agreement.
Investor takeaway: This would be a change of custodian and legal control—not, by itself, a sale of gold. The direct effect on the global bullion price should therefore be limited. The larger implications concern Venezuela’s access to hard-currency liquidity, sanctions and creditor risk, and the governance of assets that could support reconstruction.
What is confirmed—and what remains open
| Point | Current evidence | Investor relevance |
|---|---|---|
| Asset | About 31 tonnes of Venezuelan gold held at the Bank of England | Roughly 1 million troy ounces; material for Venezuela, small relative to the global gold market |
| Proposed move | London to the Federal Reserve Bank of New York | A custody transfer does not add physical supply or demand |
| Status | Reported negotiations; no final public agreement reviewed by PrimeStrider | Execution, timing and control terms remain uncertain |
| Use of proceeds | Not yet established in a binding public document | The economic impact depends on whether the gold is held, pledged or sold |
The Bank of England provides custody so central banks can hold London Good Delivery bars and access London-market liquidity. Venezuela’s bars have also been at the center of a long-running dispute over which board of the central bank had authority to direct them. That legal history makes the identity of the beneficial controller, any escrow mechanism and the conditions for use more important than the vault address alone.
Why the move matters for investors
Sovereign liquidity: If a recognised authority can pledge or sell the gold, Venezuela could convert an illiquid, contested reserve asset into funding for imports, infrastructure or reconstruction. That would be meaningful relative to the country’s constrained external financing, but it would not solve structural fiscal, monetary or oil-sector problems.
Sanctions and creditor exposure: A transfer to New York would place the asset inside a different legal and sanctions framework. Investors should not assume that relocation equals unrestricted access. U.S. licences, UK court orders, ownership provisions and potential creditor claims could still constrain transactions.
Gold-market impact: A transfer between official custodians is neutral for global supply. Only a later sale, swap or collateral transaction would create a market flow. Even then, 31 tonnes is unlikely to dominate a market driven by central-bank purchases, real yields, the dollar and broader geopolitical demand.
Bullish and bearish readings
- Constructive: A jointly accepted framework could improve transparency, unlock reconstruction funding and reduce uncertainty around part of Venezuela’s external assets.
- Cautious: The reported deal could stall, face litigation or leave control conditions unresolved. Rapid monetisation could also provide only temporary liquidity without durable institutional reform.
What to monitor next
Watch for a signed agreement, confirmation from the Bank of England or New York Fed, the named account or trustee, sanctions licences, creditor protections and a clear rule for how the gold or proceeds may be used. Those details—not the headline value—will determine the credit and macro significance.
Sources: Reuters report; Bank of England gold custody overview; UK courts case background.